A tenant relocating from London to Singapore for a fintech role in 2022 faced a familiar problem in an unfamiliar city: navigating a rental market that typically demands lengthy leases, upfront agent commissions, and furniture purchases before move-in.
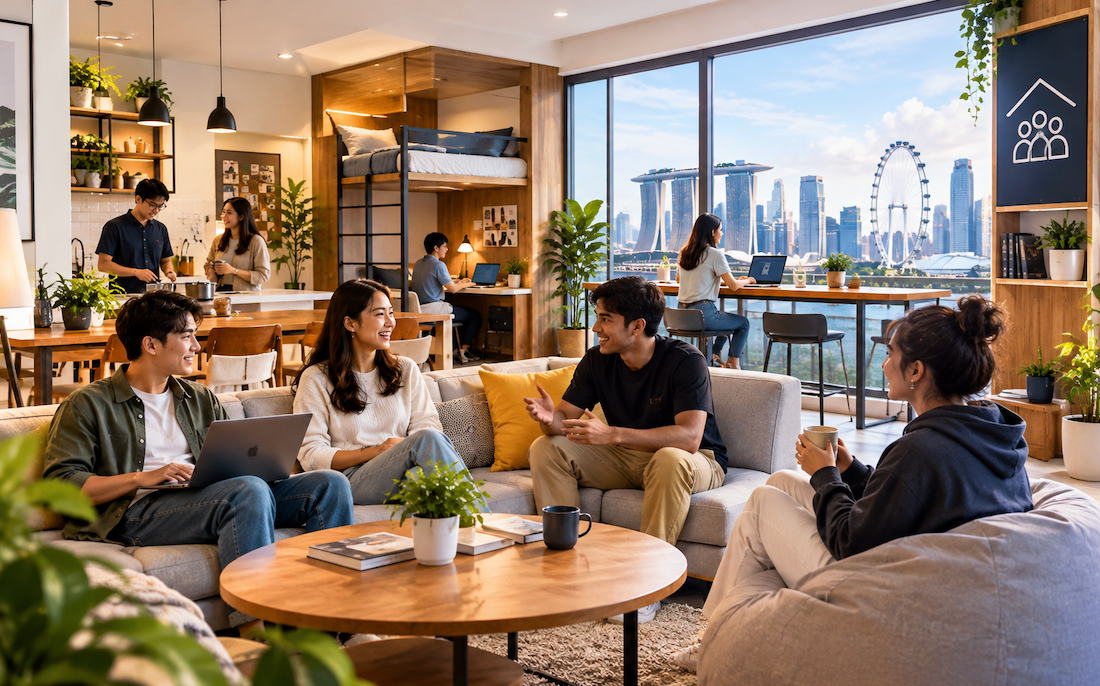
Operators like Hmlet and Coliwoo offered an alternative that had barely existed in Singapore a decade earlier, a fully furnished private room within a shared apartment or purpose-built building, bundled with utilities, cleaning, and community events, bookable on flexible lease terms sometimes as short as a few months.
That shift in how young professionals and international transplants think about housing has quietly reshaped a corner of Singapore’s rental market.
How Co-Living Operators Structure Their Business
Co-living operators typically lease entire apartments, shophouses, or purpose-built buildings from landlords on long master leases, then renovate and furnish the units before subletting individual rooms to tenants under shorter, more flexible terms than a conventional rental agreement would offer.
This master-lease model allows operators to guarantee landlords stable, predictable rental income while absorbing the operational complexity and vacancy risk of managing multiple individual tenancies themselves.
Some operators, including Coliwoo, have moved toward developing or acquiring purpose-built co-living properties rather than relying solely on leased existing stock, giving them more control over building design, shared amenities like communal kitchens and coworking lounges, and long-term asset economics.
This shift from a pure leasing model toward direct property ownership or development reflects the sector’s maturation from an early-stage rental arbitrage concept into a more capital-intensive real estate asset class in its own right.
Technology platforms underpin much of the day-to-day operation across both models, with operators using purpose-built apps to handle booking, digital tenancy agreements, rent collection, and maintenance requests without requiring the in-person paperwork typical of a traditional rental transaction.
Community management has also become a distinct operational function, with dedicated staff organizing events ranging from casual social mixers to professional networking sessions, an effort aimed at differentiating co-living from a purely transactional rental product and building the kind of tenant loyalty that supports repeat bookings and word-of-mouth referrals within relocating professional networks.
Who Chooses Co-Living Over Traditional Rentals
Young foreign professionals relocating to Singapore for work, notably those in finance, technology, and consulting roles at multinational firms, represent a substantial share of co-living demand, drawn by the convenience of move-in-ready furnished rooms and shorter lease commitments that suit uncertain initial employment tenures.
International students attending Singapore’s universities and exchange programs also form a meaningful tenant base, often preferring co-living over dormitories for greater independence or over private rentals for the built-in community aspect.
Digital nomads and remote workers on longer-term visit passes have added a newer demand segment, especially as Singapore has promoted itself as a base for location-independent professionals through various long-term visitor pass schemes.
Local Singaporean young adults have also begun using co-living spaces, especially those seeking independence from family homes without committing to the larger financial burden of purchasing or long-term renting a full flat on their own, though this segment remains smaller than the foreign professional base.
Relocation agencies and corporate mobility teams at multinational employers have also become an indirect but influential customer segment, since companies relocating staff to Singapore often steer new hires toward co-living options as a default short-term housing solution during initial settling-in periods before employees decide on a longer-term rental arrangement.
Some operators have formalized this relationship through corporate accounts offering bulk booking discounts and simplified billing for employer-sponsored stays, turning what began as an individual consumer product into a business-to-business service line generating a meaningful share of overall bookings for some operators.
Market Size and Business Growth Trends
The co-living sector in Singapore grew from a handful of small operators managing a few hundred rooms in the mid-2010s to a market encompassing thousands of units across multiple operators by the mid-2020s, with consolidation occurring as some smaller players merged or exited while better-capitalized operators like Hmlet, following its acquisition activity in the region, and Coliwoo, backed by established property group ownership, expanded their footprint.
Real estate investors have taken notice, with some co-living platforms attracting institutional capital and private equity investment as the asset class demonstrated resilient occupancy rates even through the disruption of the pandemic years.
Landlords who might once have listed a spare unit through a traditional property agent have increasingly found master leases to co-living operators an attractive alternative, trading a potentially higher per-unit rental yield for the certainty of guaranteed monthly income and reduced management burden, since the operator handles tenant turnover, maintenance coordination, and dispute resolution that a traditional individual landlord would otherwise manage directly.
Real estate developers have started designing new residential projects with co-living in mind from the outset, incorporating shared amenity floors, flexible room configurations, and infrastructure such as individual electricity submetering that make a building easier to operate as a co-living asset compared to converting an existing conventional layout after construction.
This forward integration of co-living considerations into ground-up design represents a further sign of the sector’s shift from an opportunistic use of existing rental stock toward a recognized, purpose-built category within Singapore’s broader residential development pipeline.
Regulatory Framework and Compliance Considerations
Co-living operations in Singapore operate within existing residential zoning and rental regulations, though the sector has required some regulatory clarification given its blend of hotel-like service amenities with traditional residential tenancy structures.
The Urban Redevelopment Authority has issued guidance distinguishing co-living arrangements from short-term accommodation rentals, which remain subject to stricter minimum stay requirements under Singapore’s regulations governing short-term letting of private residential property.
Operators must also navigate fire safety, building code compliance, and Housing Development Board rules where relevant, since subletting arrangements involving multiple unrelated tenants in a single unit can trigger different regulatory scrutiny than a standard single-family tenancy.
Compliance with occupancy caps per unit, a rule originally designed to prevent overcrowding, has occasionally created friction with co-living business models that aim to maximize the number of private rooms within a given floor area.
Operators have also had to navigate rules around subletting set out in individual condominium management corporation by-laws, since some private residential developments impose their own restrictions on the minimum lease term or the number of unrelated occupants permitted within a unit, restrictions that can vary widely from one development to another regardless of national-level regulation.
This building-by-building variability means co-living operators typically conduct detailed due diligence on a property’s specific management corporation rules before signing a master lease, adding a layer of site-specific complexity that a simpler single-tenant rental arrangement would not require.
Trade-Offs and Criticism of the Co-Living Model
Critics of the co-living model point to pricing that, on a per-square-foot basis, often runs higher than traditional shared rentals arranged informally among friends or colleagues, meaning the convenience premium co-living operators charge is not universally viewed as good value, not least for cost-conscious long-term residents rather than short-term arrivals prioritizing convenience over price.
Privacy concerns have also surfaced, given that co-living arrangements typically involve shared common spaces with strangers, which does not suit every tenant’s preferences even when private bedrooms offer a lockable personal space.
Turnover among co-living tenants also tends to run higher than in traditional long-term rentals, given the shorter average lease durations the model is built around, which some critics argue undermines the sense of settled community that operators market as a core part of the co-living value proposition.
A resident who arrives expecting an established social network may instead find a constantly rotating group of housemates, above all in buildings that attract a heavily transient population of short-term corporate assignees rather than a more stable mix of longer-staying tenants.
Some housing advocates have also questioned whether co-living’s growth, by absorbing a portion of the private rental supply into shorter-term, higher-turnover arrangements, has contributed marginally to tighter overall rental market conditions during periods of housing supply constraint, though operators counter that co-living primarily serves a demand segment, short-term, flexible, furnished housing, that was underserved by the traditional rental market rather than directly competing for the same long-term tenant pool.
Comparing Singapore’s Co-Living Sector Internationally
Singapore’s co-living market shares similarities with sectors in cities like London, New York, and Hong Kong, where operators such as The Collective and other international brands have pursued comparable master-lease and purpose-built models targeting young professionals.
Singapore’s relatively compact geography and dense public transport network make the co-living value proposition of centrally located, amenity-rich housing especially practical compared to sprawling cities where commute times to city-center co-living properties might otherwise undercut the model’s convenience appeal.
Japan’s share house sector, long established before co-living became a recognized global real estate category, offers a useful historical parallel, having developed its own furnished shared accommodation model largely in response to the difficulty many young Japanese renters and foreigners face qualifying for a conventional apartment lease under Japan’s traditionally strict guarantor and deposit requirements.
Singapore’s co-living sector emerged from a different starting point, driven more by demand for flexibility and convenience among a globally mobile professional workforce than by structural barriers to accessing conventional rental housing, a distinction that shapes how each market’s operators position their offering to prospective tenants.
Regional comparisons within Southeast Asia show Singapore as a more mature co-living market than neighboring cities like Kuala Lumpur or Jakarta, reflecting Singapore’s larger base of international corporate transferees and its more developed institutional real estate investment environment, which has made it easier for co-living operators to raise capital and scale operations compared to markets where real estate financing structures remain less developed for this relatively new asset class.
Future Outlook and Practical Guidance
Continued institutional investment interest suggests co-living will keep expanding as a recognized real estate asset class in Singapore, potentially with more purpose-built developments specifically designed around co-living amenities rather than retrofitted from conventional apartment layouts.
Consolidation among operators may continue, as scale advantages in procurement, technology platforms for booking and community management, and brand recognition among international relocating professionals tend to favor larger players over smaller independent operators.
Prospective tenants comparing co-living against traditional rentals should weigh the total cost of a furnished, flexible-term co-living room against the upfront costs of furnishing an unfurnished traditional rental and the value of lease flexibility given their own employment or study certainty.
Landlords considering a master lease arrangement with a co-living operator should compare the guaranteed income and reduced management burden against the potentially higher yield achievable through direct individual tenant management, factoring in their own capacity and willingness to handle tenant turnover themselves.
It is also worth reviewing the master lease contract’s break clauses and renewal terms carefully, since some early agreements signed during the sector’s rapid growth phase included terms that proved less favorable to landlords once market conditions shifted, a lesson that has led many landlords to seek shorter initial lease terms with clearer performance benchmarks before committing to a longer master lease arrangement.
What Long-Term Residents Say About Life in Co-Living Communities
Interviews and forum discussions with tenants who have stayed in co-living properties for more than a year reveal a fairly consistent pattern: the appeal is strongest in the first six to twelve months, when the built-in social calendar and low setup friction matter most, and gradually shifts toward valuing the flexibility of the lease structure once a tenant has settled into the city and formed their own social circles outside the operator’s programming.
Some long-term residents choose to stay because the all-inclusive pricing removes the mental overhead of managing separate utility accounts and appliance repairs, a convenience that matters more to busy professionals working long hours than to those with more time to manage a conventional rental.
Others eventually move to standalone apartments once they have built enough local knowledge to navigate the private rental market confidently, treating their co-living stay as a stepping stone rather than a permanent housing solution.
This split in long-term behavior suggests operators are serving two distinct customer needs simultaneously: a transitional housing product for newcomers and a lifestyle product for residents who specifically want ongoing built-in community, and the more successful operators tailor their unit mix and community programming to serve both groups without one crowding out the other.
How Co-Living Fits Into Singapore’s Broader Rental Market Structure
Co-living operates within Singapore’s wider private rental market rather than as a fully separate category, which means its growth trajectory is shaped by the same underlying forces affecting conventional rentals: interest rates that influence landlord decisions to lease rather than sell, net migration patterns that drive rental demand, and the pace of new private residential completions that affect overall supply.
When conventional rental prices rise sharply, as they did during periods of tight supply in recent years, co-living’s relative value proposition improves because tenants comparing total monthly costs, including utilities and furnishing, often find the all-inclusive co-living rate more competitive than it initially appears against a bare unfurnished rental plus separate setup costs.
Conversely, when rental supply loosens and prices soften, co-living operators face more competitive pressure from landlords willing to offer flexible, shorter leases directly, narrowing the gap that co-living’s flexibility used to command a premium for. This dynamic means co-living is best understood not as an entirely separate housing category insulated from broader market cycles, but as one flexible format within a rental market that continues to price different combinations of convenience, commitment, and cost against each other.
Final Thoughts
Co-living has grown from a niche housing concept into an established segment of Singapore’s rental market, reshaping how young professionals, students, and international arrivals think about short-to-medium-term accommodation.
Operators like Hmlet and Coliwoo have professionalized what was once an informal shared-housing arrangement, attracting institutional capital along the way.
The sector’s ability to weather the pandemic years with resilient occupancy, even as overall travel and relocation activity slowed sharply, gave institutional investors added confidence in the model’s durability across different economic cycles.
As the sector matures, expect continued consolidation, more purpose-built developments, and ongoing debate over pricing and its broader effects on Singapore’s rental housing supply. For now, the model has clearly found a durable niche between the traditional long-term rental and the short-stay hotel, one that looks set to keep growing as Singapore’s population of internationally mobile professionals continues to expand.
Whether that growth proceeds through more operators entering the market or through consolidation among the current leaders, the underlying demand driver, a city that draws talent from across the world on varying timelines, shows no sign of fading.
Frequently Asked Questions
1. How is co-living different from renting a traditional shared flat?
Co-living typically comes fully furnished, includes utilities and cleaning services in the rental price, and offers more flexible lease terms than a conventional shared flat, which usually requires tenants to furnish the space themselves and commit to a longer minimum lease. Co-living also often includes organized community events and shared amenity spaces managed by the operator.
2. Who are the major co-living operators in Singapore?
Hmlet and Coliwoo are among the most established operators in the Singapore market, alongside several smaller and regionally focused players. Ownership and scale among operators has shifted over time through mergers, acquisitions, and new capital investment into the sector.
3. Is co-living legal under Singapore’s short-term rental regulations?
Co-living arrangements are distinct from short-term rental platforms and generally comply with minimum stay requirements for private residential property, since co-living leases typically run for several months or longer rather than the very short stays restricted under Singapore’s short-term letting rules. Operators must still comply with relevant occupancy and building code regulations.
4. Why do landlords choose to master-lease to co-living operators?
Landlords benefit from guaranteed, predictable rental income and reduced management responsibility, since the co-living operator handles tenant turnover, maintenance coordination, and day-to-day tenant relations. This trade-off appeals chiefly to landlords who prefer a hands-off investment property arrangement over maximizing per-unit rental yield.
5. Is co-living more expensive than a traditional rental?
On a per-square-foot basis, co-living often costs more than an informally arranged shared rental, reflecting the value of furnishing, flexible lease terms, bundled utilities, and included services. Whether it represents good value depends on a tenant’s need for flexibility and convenience relative to long-term cost minimization.
6. Who typically lives in co-living spaces in Singapore?
The tenant base skews toward young foreign professionals relocating for work, international students, and digital nomads on longer-term visitor passes, though a growing number of local young adults also use co-living spaces for independent living without a long-term rental commitment.